Weekly Report on Bulk Textile Material (II), Mar. 16th-20th
Author: Mar 26, 2015 09:26
|
1. Review of raw material market
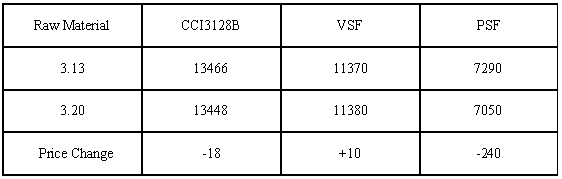
Cotton: The domestic cotton spot market went higher slightly this week. Although the inquiry was not a few, the sales situation was still not optimistic. The buyers thought that the cotton price would continue to be downward and the wait-and-see mood was very strong. According to Cotlook news, the cotton export in India was about 650-750 million bales (110-128 million tons) until the end of January, account for 70%-80% of total exports this year. This week the Indian domestic cotton demand and export took a turn for the better, the procurement from Pakistan textile manufacturer was still negative and just waited for the direction of the market. Despite parts of cotton ginning mill still kept prices unchanged and a few suppliers had started to cut prices in order to attract buyers. Meanwhile, the cottonseed oil and cottonseed meal had fallen in price and the market transaction was general.
VSF: The market transaction center of viscose staple fiber had come under downward pressure this week, the whole purchasing capacity was insufficient in the market. The de-stocking intention was stronger than before due to the higher pressure and lower price. Now the mainstream negotiating price of middle-end goods stayed at 11,500-11,700 Yuan/ton, the high-end goods were quoted at 11,600-11,800 Yuan/ton. The market was lack of confidence and the manufacturer was unwilling to purchase more goods. In the aspect of the upstream market, the price of rayon flock and cotton pulp was smooth as a whole. Now the negotiating price of short velvet was 2,500 Yuan/ton in the South and it was quoted at 2,250 Yuan/ton in Xinjiang region. The cotton pulp price stayed at 6,100 Yuan/ton. It was difficult to rise owing to the fallen price of the viscose staple fiber. In the aspect of the downstream market, the spun rayon yarn went weak while maintaining the stability. The negotiating price of Sirospun 40S was 18,200-18,400 Yuan/ton in Fujian area and 30S was quoted at 17,800-18,000 Yuan/ton in Jiangsu region. At present, the trading atmosphere of the viscose staple fiber was not enough and the manufacturer price was a bit loose. It was expected that the price would be consolidated by weakness in afternoon market.
Nylon: This week the nylon market went weak as a whole, the upstream cost began to drop and the price trends fell accordingly. Now the quotation of nylon high-speed spinning chips maintained stable, the mainstream quotation of low-end goods was 13,800-14,000 Yuan/ton and the market procurement mood followed up step by step. The light nylon chips were quoted at 15,500-16,000 Yuan/ton and the manufacturer inventory was at 10-15 days. At present, the upstream cost of chip manufacture was loose obviously due to the sluggish demand and higher inventory. Now the operating rate fo nylon manufacturer was about at 70%. The production and marketing was difficult to balance due to the insufficient demand. It was expected that the quotation of the nylon chips would be consolidated by weakness.
2. Focal point in China market
1) The rigid demand was insufficient and the production and marketing of new orders continued to hover low.
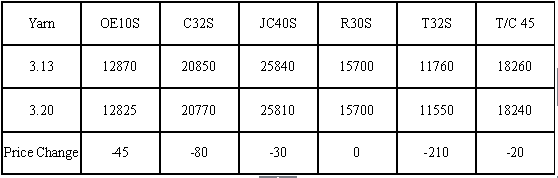
 Up to the 20th of March, the downstream manufacturer thought that the afternoon market was optimistic and kept the wait-and-see mood. The transaction was dominated by the small orders, the production and marketing of new orders remained low and the price fell slightly.
As of the 20th of March, the yarn price had fallen in prices while maintaining the stability, because the factory operating enthusiasm was not high, coupled with the previous inventory pressure.
 Recently the nylon yarn price went lower slightly due to the inhibition of the upstream and downstream market. The market transaction of FDY was cold and the price stabilized. The semi-bright FDY70D/24F was quoted at 18,200-18,500 Yuan/ton in Jiangsu and Zhejiang region and the inventory could remain ar 20-30 days. Meanwhile, the downstream demand of DTY was slow, the middle-end DTY70D/24F was quoted at 20,000-21,000 Yuan/ton and the wait-and-see mood was more strong in the downstream. Furthermore, the cash price of POY was back to 16,500-17,000 Yuan/ton in Zhuji region and the inventory could remain 15 days. At present, the excess production capacity of nylon industry chain was significant, the market still had inventory pressure, combined with the downstream textile customers purchasing follow up slowly. It was expected that the price was difficult to be better in the afternoon market.
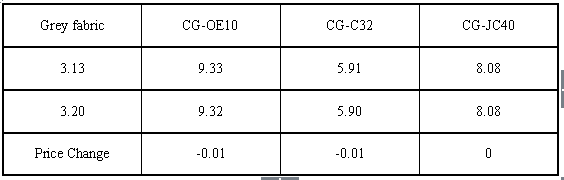 As of the 20th of March, the whole trading atmosphere rose compared with the previous period in the market. The manufacturer consumed the early inventory, coupled with the upstream raw materials fell slightly, the cost loose obviously.
3)Theory profit of spinning and nylon
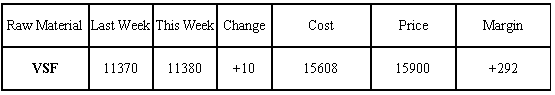 As of the 20th of March, according to C32S cotton index was 21,500 Yuan/ton, CCI 328B index was 17,466 Yuan/ton, the textile manufacturer spinning was losses of 106 Yuan/ton.
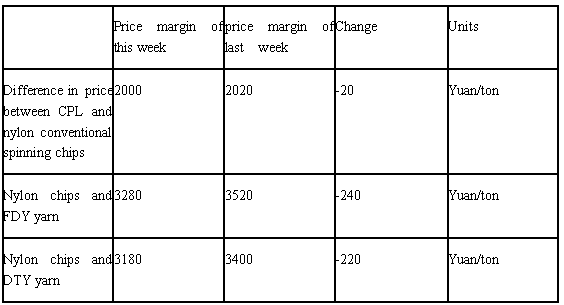
At present, the difference in price between CPL domestic market and nylon conventional spinning chips was 2,000 Yuan/ton. The profits of chip manufacturer rose slightly due to the loosing upstream cost. Recently nylon yarn price went weak while maintaining the stability and the market transaction was soft, especially FDY which the market price declines significantly. From the price margin, the current price margin between FDY70D/24F and conventional spinning chip was 3,280 Yuan/ton, the manufacturer was still at a break-even level. Similarly, the different in price between DTY70D/24F and conventional spinning chips stayed at 3,180 Yuan/ton or so, the manufacturer had not any profits.
 3. Downstream market and market forecast
The resumption of work was faster than before in the domestic cotton textile companies until this week, the operating situation put off. The demand remained low due to the unrecovered operation. At present, the products offered smoothly in the textile market and the trading atmosphere was weak. So far, the import yarn quantity increased obviously this month. However, the purchasing intention was not strong in the domestic market, which was given priority to rigid demand. In the aspect of the downstream market, the all cotton yarn price fluctuated slightly this week.
|
Editor: sunny From: 168Tex.com
Most Read