Weekly Report on Bulk Textile Material (II), Mar. 9th-16th
Author: Mar 18, 2015 09:20
|
1. Review of raw material market
Cotton: The domestic cotton price was dominated by stability this week. On one hand, due to the poor quality and a little orders, the trading atmosphere of the cotton was not ideal in the domestic market. In addition, the transaction of spot goods in the port was also cold and there were little orders. On the other hand, the cotton price in India maintained stable, while the demand from the textile factory and traders were general in the overseas market. Meanwhile, the cottonseed oil had fallen in price stability. Although the cotton linters rose, while the market confidence tended to be weak.
VSF: The market price of viscose staple fiber was a bit loose this week. The de-stocking intension was strong in the viscose staple fiber manufacturer due to the poor enthusiasm from the downstream textile mill and higher inventory pressure, which the transaction price declined while maintaining the stability in the market. At present, the leading negotiating price of the middle-end products stayed at 11,300-11,400 Yuan/ton, the high-end goods were quoted at 11,500-11,600 Yuan/ton. In the aspects of the upstream market, the market quotation of the linter and cotton pulp changed little. Now the cotton linter was quoted at 2,600 Yuan/ton and the long velvet was 3,300 Yuan/ton. Along with the influence of the viscose staple fiber, the cotton pulp price stayed at 6,000 Yuan/ton. In the aspects of the downstream market, the trading atmosphere of the spun rayon yarn was general. Now 30S was quoted at 17,100 Yuan/ton in China-Xiaoshan and Shaoxing region. It was expected that the market price would be further declined next week because of the sluggish demands for the viscose staple fiber.
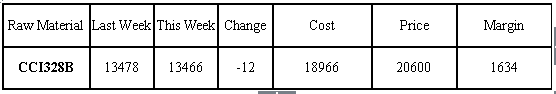
Nylon: This week the nylon market quotation declined slightly. Now the semi-bright chips of nylon went low in China-Zhejiang region, the high-end products were quoted at 13,500 Yuan/ton and the inventory was about 10-15 days with 85% of the operating rate. The high-speed spinning nylon chips were stable in China-Jiangsu area, now the negotiating price was 14,800-15,200 Yuan/ton and the demands were general in the downstream. At present, the upstream cost of chips manufacturer would be soft due to the sluggish price and higher inventory. It was expected that the nylon chips would continue to stalemate.
2. Focal point in China market
1) The downstream demands were insufficient to follow up, the de-stocking intention of the supplier was stronger.
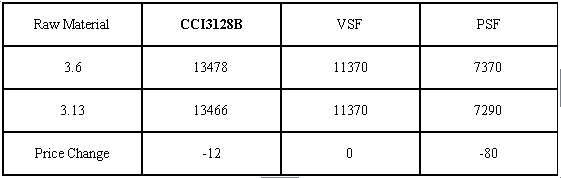 Up to the 13th of March, the price was lower than the previous due to the poor raw material purchasing enthusiasm from the downstream textile mill and the strong wait-and-see mood, and the de-stocking intention was higher than before in the manufacturer.
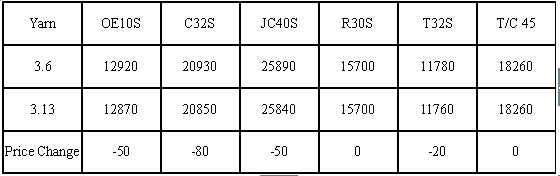
As of the 13th of March, the yarn price declined while maintaining the stability because of the lower operating enthusiasm and the higher inventory pressure.
 Recently, the nylon yarn had different performance, among which FDY products were dominated by stability. Now the ex-factory price of FDY70D/24F was 18,200 Yuan/ton. The price of DTY products changed little, DTY70D/24F stayed at 16,700 Yuan/ton in China-Zhuji region. Meanwhile, POY demands were general in the downstream, now the low-end POY85D/24F was quoted at 21,000 Yuan/ton.
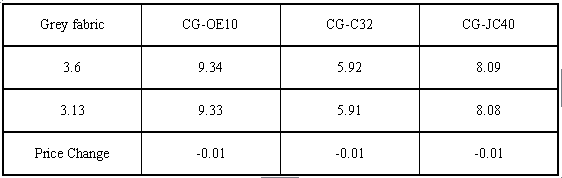 As of the 13th of March, the rate of operation was roughly recovery and the price went weak while maintaining the stability.
2)Theory profit of spinning and nylon
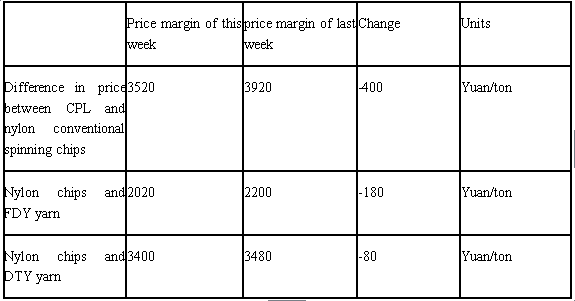
 At present, the difference in price between CPL domestic market and nylon conventional spinning chips was 3,520 Yuan/ton and the chips profit declined slightly. The market price of nylon yarn went stable. The products price of most specifications of FDY, DTY, and POY went weak. From the price margin, the current price margin between FDY70D/24F and conventional spinning chip was 2,020 Yuan/ton, the manufacturer was still at a break-even level. Similarly, the different in price between DTY70D/24F and conventional spinning chips stayed at 3,400 Yuan/ton, the manufacturer had not any profits.
 3. Downstream market and market forecast
In the aspect of the downstream market, the cotton spot price increased slightly. The individual manufacturer conveniently improved the cotton yarn price in order to stimulate the market recovery. However, due to the annual national cotton purchase policy would be ended on March 31, it was expected that the cotton price would be downward. Therefore, because of the limited support strength for the all cotton yarn, the cotton price was difficult to improve. It was expected that the all cotton yarn price would be weaken in afternoon market.
|
Editor: sunny From: 168Tex.com
Most Read