Weekly Report on Bulk Textile Material (II), Mar. 2nd-6th
Author: Mar 11, 2015 09:25
|
1. Review of raw material market
Cotton: The spot price of cotton in China declined slightly this week. According to the reflection of some warehouse in Shandong, Hebei and Henan province etc., the imported cotton price kept firm and some small and medium-sized enterprises had not started in the domestic market. The actual transaction was sluggish in spite of the good inquiry. On the other hand, the cotton market continued to be down in Pakistan and the textile enterprises were cautious of the procurement. The ginning plant offered firm, the demand of the imported cotton was good which mainly imported India S-6 cotton. In India, due to the higher price and negative purchasing from exporters, the domestic cotton demands were general in India and the recent acquisition sped up than before. Meanwhile, the cottonseed oil had fallen in price stability and the price of cottonseed meal stopped falling and stabilized.
VSF: This week the quotation of viscose staple fiber rose slightly this week, the individual viscose staple fiber manufacturers wanted to increase the price after the Spring Festival and the market quotation rose to 12,800 Yuan/ton, other viscose staple fiber manufacturers also pulled up, but the downstream market was lack of the purchasing strength and motivation, the manufacturer consumed the raw material inventory and the demand for the viscose staple fiber was not high. The negotiating price of middle-end product was 11,400 Yuan/ton and the high-end product was 11,600 Yuan/ton. The manufacturer mainly performed the backlog of orders and the production-and-marketing of new orders was about 10-30%. In the upstream market, the market price of rayon flock and cotton pulp went stable. Many traders were unwilling to sell because the oil factory had not in service. Now the rayon flock was quoted at 2,600 Yuan/ton in China-Shandong region and the price of cotton pulp stayed at 5,900 Yuan/ton, which with little change compared with the previous year. In the downstream market, the spun rayon yarn followed by a sluggish recovery, the manufacturer had different operating conditions, the de-stocking intention was obvious in the dividual factory and the quotation stabilized temporarily. At present, some manufacturers mainly performed the early orders and the inventory was still in a reasonable space. It expected that the market demand maybe had not a big improvement in the short term and the market price was consolidated.
Nylon: This week the nylon market quotation increased slightly than before. Now the low-end conventional spinning nylon products were quoted at 15,700-15,800 yuan/ton in East China and the high-end high-speed spinning nylon chips were 15,500 Yuan/ton in China-Fujian region. The market demand rebounded back and the whole transaction was general. At present, the chips market was difficult to be better due to the higher inventory than before, combined with the sluggish price of CPL in the upstream market and weak demands. It was expected that the nylon chips market would be in a stalemate in the short term.
2. Focal point in China market
1) The transaction of staple fibre was scarce and the procurement need to be careful.
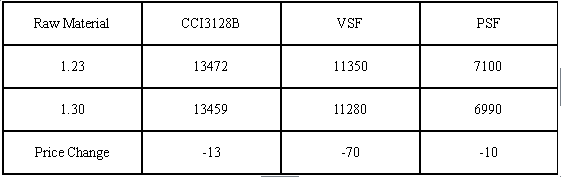 Up to the 16th of March, the cotton and viscose staple fibre was lower than before and the polyester staple fibre price was rebounded slightly. The cotton transaction was relatively rare and was lack of effective orders.
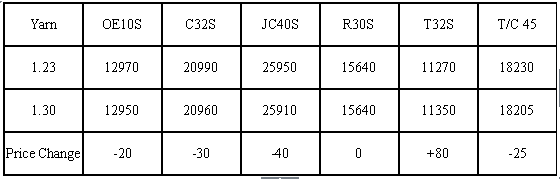 Recently, the nylon yarn price went stable, among which POY price quoted a little higher and other products changed little. Now the semi-light FDY70D/24F was quoted at 19,700-19,800 Yuan/ton and 40D was 25,000-26,000 Yuan/ton in Jiangsu and Zhejiang area. Meanwhile, the market quotation of POY85D/24F was 18,000-18,250 Yuan/ton in Zhuji region. The rate of operation was about 50%-80%. Due to the current raw material cost support in the downstream, it was expected that the price would be still firm in the short term.
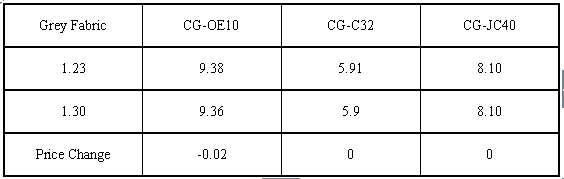 Up the the 16th of March, the market recovery was slow as a whole, the trading atmosphere was cold, the factory inventory pressure was large before the Spring Festival and the de-stocking intention was obvious by the manufacturer. Although the price declined, while the actual transaction was not big.
2) Theory profit of spinning and nylon
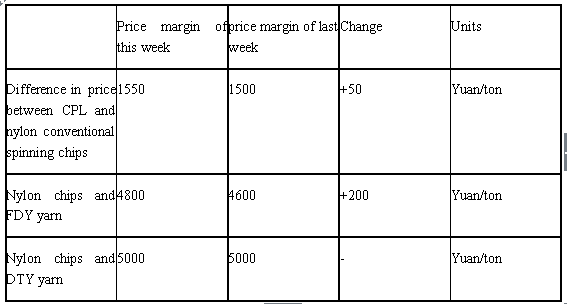
At present, the difference in price between CPL domestic market and nylon conventional spinning chips was 1,550 Yuan/ton and the chips profit rebounded slightly. The market price of nylon yarn went stable. The products price of most specifications of FDY, DTY, and POY was consolidation. From the price margin, the current price margin between FDY70D/24F and conventional spinning chip was 4,800 Yuan/ton, the manufacturer was still at a break-even level. Similarly, the different in price between DTY70D/24F and conventional spinning chips stayed at 5,000 Yuan/ton, the manufacturer had not any profits.
 3. Downstream market and market forecast
In the aspect of downstream, the trading atmosphere of cotton yarn was sluggish this week and the recovery was slow. Although the manufacturer started to operate, while the wait-and-see mood was strong. The rate of operation in some cotton mills was still poor due to the sluggish market and some manufacturer still consumed the inventory. It was expected that the 100% cotton yarn would continue to be weaken.
|
Editor: sunny From: 168Tex.com
Most Read